
Key Takeaways
- H5322-025 is a UnitedHealthcare Dual Eligible Special Needs Plan (D-SNP) for 2026 in Texas that requires qualifying for both Medicare and Medicaid; eligibility varies by county, so verify your specific address and status before enrolling.
- The plan offers $0 monthly premium, $0 medical deductible, and $0 copays for annual wellness exams and telehealth, but includes a $9,250 in-network out-of-pocket maximum and $464 Part D deductible.
- As an HMO-POS plan, H5322-025 requires using in-network providers and obtaining referrals for specialists, though point-of-service options allow some out-of-network care at higher costs.
- The plan includes extra wellness benefits like fitness programs, dental, vision, hearing aids, and non-emergency medical transportation that Original Medicare doesn't cover by default.
- Always verify enrollment status, network provider participation, and referral requirements before scheduling appointments to avoid unexpected bills and ensure continuous coverage.
- Dual-eligible individuals should consult their Medicaid caseworker about how their status affects cost-sharing, as Medicaid often covers out-of-pocket costs that Medicare leaves uncovered.
If you have seen the code H5322-025 on a Medicare letter or plan comparison site, you may be wondering what it actually means for your care. This identifier points to a specific Medicare Advantage plan, and understanding it can help you make a smarter choice for your health coverage in 2026. Whether you are helping an aging parent sort through mail or comparing your own options, knowing the difference between this plan and Original Medicare matters.
This guide breaks down what H5322-025 covers, who qualifies, and how it compares to traditional Medicare. We will also look at what this means for your everyday primary care needs, from annual wellness visits to chronic disease management. Understanding your coverage is one of the first steps toward getting consistent, quality care from a primary care provider you trust.
What Is H5322-025?
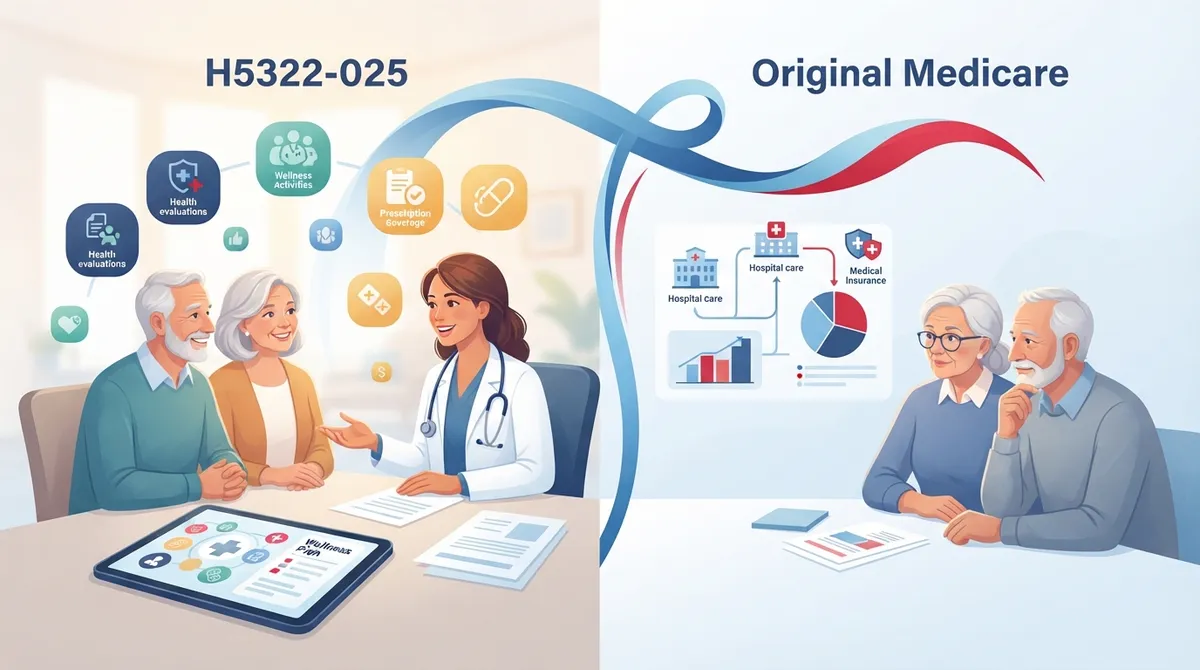
H5322-025-0 is a plan identifier used by the Centers for Medicare & Medicaid Services (CMS). It identifies UnitedHealthcare's UHC Dual Complete TX-D007 plan for the 2026 plan year. You may also see it written without the last digit, as H5322-025.
This is not a billing code or diagnosis code. It is simply a way for CMS to track and organize a specific insurance plan. The plan itself is a Dual Eligible Special Needs Plan, often shortened to D-SNP. These plans are built for people who qualify for both Medicare and Medicaid at the same time.
Breaking Down the Plan Type
The plan works as an HMO-POS. This stands for Health Maintenance Organization with a Point-of-Service option. In simple terms, it means members usually need to use doctors within a set network. However, the point-of-service feature allows some flexibility to see out-of-network providers under certain rules.
Here is what that structure means in practice:
- You typically choose a primary care doctor within the plan's network
- Referrals may be needed to see specialists
- Some out-of-network care is allowed, but it may cost more
- Emergency care is usually covered regardless of network status
Always check your Evidence of Coverage document for exact rules. Plan details can change every year, so what applied in 2025 may look different in 2026.
Who Can Enroll in This Plan?
Eligibility for H5322-025 depends on two main factors. First, you must qualify for both Medicare and Medicaid. Second, you must live in one of the Texas counties where the plan is offered.
Simply seeing this plan name does not mean you automatically qualify. Coverage rules vary by county, and Medicaid eligibility can shift based on income and other factors. If you are unsure, contacting Medicare directly or speaking with a licensed agent is the safest way to confirm your status.
Where Is the Plan Available?
This plan is offered in specific counties across Texas. Some documented service areas include Hardin County, Falls County, Frio County, and Taylor County. Availability can differ by ZIP code even within the same county, so it helps to check your specific address against the plan's official service area listing before assuming you are covered.
2026 Costs and Coverage Details
Third-party plan listings report the following details for the 2026 plan year. These numbers can change, so always confirm with official plan documents before making decisions.
|
Cost Category |
2026 Reported Amount |
|---|---|
|
Monthly Plan Premium |
$0 |
|
Medical Deductible |
$0 |
|
In-Network Medical Out-of-Pocket Max |
$9,250 |
|
Part D Prescription Deductible |
$464 |
|
Annual Wellness Exam Copay |
$0 |
|
Telehealth Copay |
$0 |
Keep in mind that the Medicare Part B premium may still apply, even with a $0 plan premium. Medicaid status can also affect what a dual-eligible member actually pays out of pocket. A third-party listing reported roughly 29,106 enrollees in this plan for 2026, though enrollment numbers shift over time.
What Benefits Are Included?
Beyond basic medical coverage, this D-SNP plan reportedly includes several additional wellness benefits. These extras are common in Medicare Advantage dual-eligible plans, since they aim to support whole-person health rather than just treating illness after it happens.
- Fitness program access
- Dental coverage
- Vision benefits
- Hearing aid coverage
- Over-the-counter allowance for health products
- Non-emergency medical transportation
- Part D prescription drug coverage with an enhanced formulary
These benefits reflect a broader trend in wellness-focused healthcare, where prevention and support services matter as much as treating sickness. Even if you are not on this exact plan, it is worth asking your own Medicare plan what similar wellness perks it might offer.
H5322-025 vs. Original Medicare: Key Differences
So how does this Medicare Advantage D-SNP plan actually stack up against Original Medicare? Here is a straightforward comparison to help you understand the tradeoffs.
|
Feature |
H5322-025 (D-SNP) |
Original Medicare |
|---|---|---|
|
Provider Network |
HMO-POS network required |
Any provider accepting Medicare |
|
Monthly Premium |
$0 (reported) |
Varies; Part B premium applies |
|
Prescription Drugs |
Included (Part D) |
Requires separate Part D plan |
|
Dental/Vision/Hearing |
Often included |
Not covered by default |
|
Referrals Needed |
Often required for specialists |
Not required |
|
Eligibility |
Medicare + Medicaid dual status |
Medicare eligibility only |
Original Medicare offers more freedom to see any provider, but it lacks the extra wellness benefits many D-SNP plans include. For dual-eligible individuals, plans like H5322-025 can reduce out-of-pocket costs significantly since Medicaid often covers what Medicare does not.
Steps to Verify Your Coverage
If you think you might be enrolled in this plan, or you are considering it, follow these steps to confirm the details.
- Locate your Medicare card or plan enrollment letter to check the exact plan ID
- Visit Medicare.gov or call 1-800-MEDICARE to confirm your enrollment status
- Request the current Evidence of Coverage and Summary of Benefits from UnitedHealthcare
- Confirm your county of residence matches the plan's service area
- Check whether your preferred doctors are in the plan's network
- Ask your Medicaid caseworker how your dual-eligible status affects cost-sharing
Never assume coverage based on a plan name alone. Rules, provider networks, and benefit details can change from one plan year to the next.
Why Coordinated Primary Care Still Matters
Regardless of which Medicare plan you carry, having a dependable primary care relationship is one of the best things you can do for your long-term health. A good primary care doctor helps you stay ahead of chronic conditions, catch problems early, and avoid unnecessary emergency room visits.
At InCare, our team understands how confusing Medicare and Medicaid coverage can feel. We help patients make sense of their benefits while focusing on what matters most, which is your health. Our providers take time to explain your options and coordinate care that fits your specific situation, whether you are managing diabetes, high blood pressure, or simply need an annual wellness visit.
Services That Support Whole-Body Health
Beyond basic checkups, InCare offers services designed to help you stay ahead of health issues before they become serious. These include:
- Cancer screening for early detection
- Weight loss programs backed by medical guidance
- DNA gene testing for personalized health insights
- IV hydration and vitamin drips for energy support
- Urgent care for same-day illness and injury needs
Whether your coverage comes from a Medicare Advantage plan, Medicaid, or private insurance, having access to this range of services under one roof makes managing your health far simpler.
Common Mistakes to Avoid
Many patients run into avoidable problems when navigating Medicare Advantage D-SNP plans like H5322-025. Here are a few mistakes worth watching for.
- Assuming a $0 premium means there are no other costs involved
- Skipping the step of confirming network status before booking an appointment
- Forgetting that Medicaid rules can change your actual out-of-pocket spending
- Not asking about referral requirements before seeing a specialist
- Failing to re-check plan benefits each year, since details can shift annually
Taking a few extra minutes to verify these details can save you from unexpected bills or delayed care later.
For Healthcare Providers: What to Confirm Before Treatment
If you are a clinical provider treating a patient with this plan, a few verification steps are essential. UnitedHealthcare's provider guidance for the 2026 TX-D007 plan confirms it is a D-SNP for people eligible for both Medicare and Medicaid. Before providing non-emergency services, confirm the following:
- Current enrollment status and active coverage dates
- Whether your practice is in-network for this specific plan
- Referral requirements for any specialty services
- Applicable cost-sharing based on the patient's Medicaid status
This verification protects both the patient and the practice from billing surprises down the road.
Making the Right Choice for Your Health Coverage
Choosing between a Medicare Advantage D-SNP plan and Original Medicare depends on your personal health needs, your Medicaid eligibility, and how much flexibility you want in choosing providers. Plans like H5322-025 can offer valuable extra benefits for dual-eligible individuals, but they come with network restrictions that Original Medicare does not have.
Whatever coverage you choose, pairing it with consistent primary care makes a real difference in your long-term health outcomes. Our team at InCare has built a reputation for patient-first care across Tampa and Riverview, and you can visit us on Google — InCare to see what our patients are saying. You can also follow our updates and health tips on Facebook, Instagram, and TikTok.
If you have questions about your coverage or want to establish care with a provider who takes time to understand your full health picture, our team is ready to help. Reach out to our team today or schedule your appointment now to take the next step toward better managed, whole-body care.
FAQs
Q: What is Medicare plan H5322-025?
A: H5322-025 is a CMS plan identifier for UnitedHealthcare's UHC Dual Complete TX-D007, a Medicare Advantage Dual Eligible Special Needs Plan for the 2026 plan year in Texas. It serves people who qualify for both Medicare and Medicaid.
Q: Who is eligible for UHC Dual Complete TX-D007?
A: Eligibility requires qualifying for both Medicare and Medicaid, along with living in one of the plan's approved Texas counties. Simply seeing the plan name does not guarantee enrollment eligibility.
Q: Does H5322-025 cover primary care and annual wellness visits?
A: Yes, third-party listings report a $0 copay for the in-network annual wellness exam and telehealth services. Coverage conditions and network rules still apply, so confirming with official plan documents is recommended.
Q: Can I see a doctor outside the network with this HMO-POS D-SNP?
A: The point-of-service feature allows some out-of-network access, but it typically comes with higher costs. Reviewing the plan's Evidence of Coverage will clarify exact rules and expenses.
Q: What are the 2026 premiums and out-of-pocket costs for H5322-025?
A: Third-party listings report a $0 monthly premium, $0 medical deductible, and a $9,250 in-network out-of-pocket maximum. The Medicare Part B premium may still apply separately.


