
Key Takeaways
- Verify your doctor's network status by calling their office directly with the exact plan name and ID, as provider directories can lag behind actual changes and this is the single most important step before enrolling.
- Out-of-pocket maximums range from $3,300 to $6,900 depending on your county, so compare total yearly costs (premium + copays + maximum) rather than focusing only on the $0 monthly premium.
- Benefits, copays, networks, and out-of-pocket limits vary significantly by county and change annually, so always confirm current details in official 2026 plan documents before making decisions.
- $0 primary care copays encourage preventive visits that catch problems early and support chronic disease management, making this benefit valuable for establishing a strong primary care relationship.
- HMO plans restrict you to in-network providers except emergencies, and some require specialist referrals, so confirm these rules and whether your key specialists are in the network before enrolling.
- Confirm which extra benefits like dental, vision, and transportation are available in your specific county and their yearly dollar limits, as these vary widely and are not standardized across all service areas.
Choosing a Medicare Advantage plan is a big decision, and the plan name rarely tells the full story. The Cigna Preferred Savings Medicare HMO is one plan that draws attention because of its low monthly premium and its $0 primary care visits in the plan examples reviewed. But what does that mean for your day-to-day health care in 2026?
This guide explains how the Cigna Preferred Savings Medicare HMO works, what it may cost, and how HMO rules affect your choice of primary care doctor. You will also learn which questions to ask before you enroll, and how to confirm that your doctor is in the network. Benefits vary by county and plan year, so every number here should be checked against your local plan documents.
Whether you are new to Medicare or reviewing your options during an enrollment period, a clear picture of how your plan connects to preventive care can help you make a confident choice.
What Is the Cigna Preferred Savings Medicare HMO?
The Cigna Preferred Savings Medicare HMO is a Medicare Advantage plan sold in specific local service areas. It is not one nationwide benefit package. Copays, provider networks, and out-of-pocket limits can change from one county to the next.
A Medicare Advantage plan replaces Original Medicare for your day-to-day coverage. It includes Medicare-covered medical care. In the plan examples reviewed, it also includes Part D prescription drug coverage. Extra benefits, such as dental or vision, depend on the plan in your area.
One more point matters in 2026. Plan branding can change. A related plan called HealthSpring Preferred Savings (HMO) appears in 2026 materials for Texas. Always confirm the current insurer name, plan ID, and county availability in official plan documents.
How an HMO Network Affects Your Care
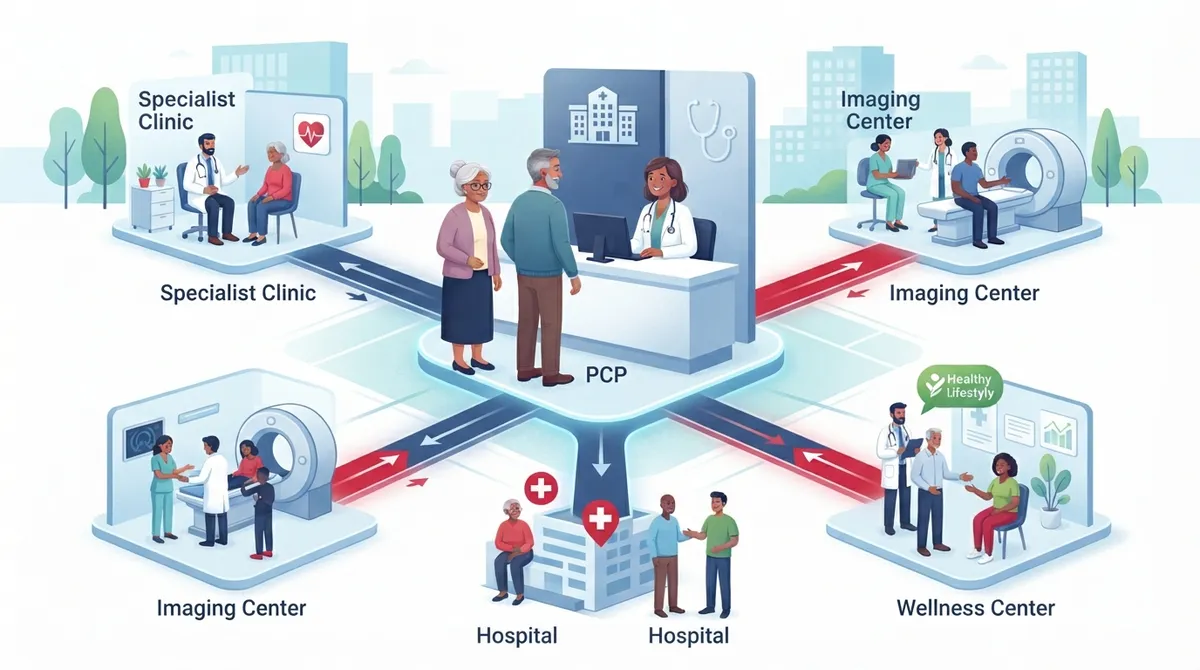
HMO stands for Health Maintenance Organization. In simple terms, you use doctors, hospitals, and other providers that belong to the plan's network. Emergencies and certain exceptions are the main times you can go outside the network.
Here is what that means in practice:
- Network matters: Care from out-of-network providers may not be covered, except in emergencies or other plan-approved cases.
- Primary care anchors your care: Many HMO members choose a primary care physician to coordinate their health needs.
- Referral rules may apply: Some plans require a referral before you see a specialist. Check the Evidence of Coverage for exact rules.
This structure can work well for people who value one main doctor who knows their full health story. It can feel limiting for people who want to see many specialists without approval steps.
Key Costs in the Plan Examples Reviewed
The 2025 plan documents reviewed give a useful snapshot of how this plan is built. The table below summarizes what those examples showed. Treat these figures as examples, not as a promise for your county or for 2026.
|
Benefit |
What the 2025 Examples Showed |
|---|---|
|
Monthly plan premium |
$0 (you generally still pay the Medicare Part B premium) |
|
Primary care visit |
$0 for in-person or telehealth visits |
|
Specialist visit |
$30 to $45 per visit, depending on area |
|
In-network medical out-of-pocket maximum |
$3,300, $4,000, or $6,900, depending on area |
|
Prescription drug coverage |
Included in the examples reviewed |
A 2026 HealthSpring-branded summary for seven Texas counties lists a $0 monthly premium and a $7,200 in-network medical out-of-pocket maximum. This shows how limits can shift from year to year and region to region.
Understanding the Out-of-Pocket Maximum
The out-of-pocket maximum is the most you would pay in a year for covered Medicare Part A and Part B services. It acts as a safety net if you face a serious illness or surgery. It does not necessarily include prescription drug costs or services the plan does not cover.
Because the examples ranged from $3,300 to $6,900, this number deserves close attention. A lower premium can sometimes come with a higher out-of-pocket limit, so look at both together.
Why $0 Primary Care Visits Matter
A $0 copay for primary care can remove a common barrier. When a visit costs nothing, you are more likely to go in for a checkup, a new symptom, or a medication review. Early visits often catch small problems before they grow.
Primary care is the foundation of good health in later years. A strong primary care relationship supports:
- Preventive screenings that find problems early.
- Chronic condition management for issues like blood pressure and diabetes.
- Medication reviews to avoid duplicates and harmful interactions.
- Referrals and coordination when you need a specialist.
To learn what a good visit includes, read what happens during an annual wellness visit. For a wider view of the role your doctor plays, see what a primary care physician does for your health.
Who Can Enroll
In general, you must meet a few basic rules to join a Medicare Advantage plan like this one:
- You have Medicare Part A and Part B.
- You live in the plan's service area.
- You enroll during a valid Medicare enrollment period.
- The plan is available in your county for the plan year.
Plan availability is the part that trips up many people. A plan that exists in one county may not be offered in the next one over. Confirm your county before you compare costs.
Extra Benefits to Verify
Medicare Advantage plans often advertise extras beyond Original Medicare. These may include dental, vision, hearing, transportation, fitness programs, or over-the-counter allowances. Availability and dollar limits vary, and the research reviewed here does not confirm a standard list for this plan.
Ask the plan these direct questions before you enroll:
- Which extra benefits are included in my county?
- What are the yearly dollar limits on each one?
- Do I need prior approval for any of them?
- Are the providers for these benefits in the network?
One Florida plan example also advertised a Part B premium reduction. The amount and who qualifies are plan-specific, so confirm the details in writing.
How to Check Whether Your Doctor Is in the Network
The single most important step is confirming your doctor's network status. A plan can look perfect on paper and still fail you if your trusted physician does not participate.
Follow these steps:
- Get the current provider directory from the plan's official website or by phone.
- Search for your doctor by name and note the exact location.
- Call the doctor's office and ask if they accept this exact plan name and plan ID.
- Check your hospital and specialists the same way.
- Ask about your prescriptions and confirm they appear on the plan's drug list.
Doctors' offices can tell you which plans they accept. Directories can lag behind real changes, so a phone call adds a useful second check. For more help, see how to find doctors accepting new patients near you.
Comparing This Plan With Other Options
No single plan fits everyone. Use a short checklist when you compare Medicare Advantage options in your area.
- Total yearly cost: Add premium, copays, and the out-of-pocket maximum.
- Doctor access: Confirm your primary care doctor and key specialists are in the network.
- Drug coverage: Check that your medications and pharmacy are covered.
- Referral rules: Learn how easy it is to see a specialist.
- Extra benefits: Weigh what you will truly use.
You can also explore how plan types differ in this guide to Medicare Advantage plans and primary care. If you want a deeper look at HMO design, read what a Medicare HMO is and how it covers care.
Making the Most of an HMO Plan
An HMO rewards people who use it well. A few habits can improve both your health and your costs.
- Pick a primary care doctor early. A steady relationship helps with coordination.
- Use telehealth when it fits. The plan examples listed $0 telehealth primary care visits, which can save time.
- Schedule preventive care. Annual wellness visits and screenings are best used every year.
- Stay in network. This avoids surprise bills.
- Keep your medication list current. Bring it to every appointment.
These habits matter for many readers, including busy adults who help manage a parent's coverage. If you help a family member, you may also like 7 traits of the best Medicare provider for primary care.
Where Primary Care and Wellness Fit In
Insurance pays for care, but it does not replace a good care team. The best results come when a plan and a strong primary care practice work together.
InCare is a personalized primary care and wellness clinic with locations in Tampa and Riverview, Florida. The team combines modern technology with medical expertise to support prevention and whole-body health. Services include primary care, urgent care, and cancer screening. InCare also offers wellness options such as weight loss programs, and DNA gene testing. Virtual visits are available too, which suits people who like to manage care from home.
Plan participation differs by practice, so check with InCare directly about which insurance plans it accepts before you book. You can see what patients say by visiting our InCare location on Google. You can also follow the clinic on Instagram, Facebook, or TikTok for health tips and updates.
If you want help understanding Medicare coverage in the Riverview area, this article on what seniors need to know about a Medicare doctor in Riverview is a useful next read.
Common Mistakes to Avoid
Many people choose a plan based on one number, such as the premium. That can backfire. Watch for these common errors:
- Ignoring the network. A low premium means little if your doctor is out of network.
- Skipping the drug list. A plan that does not cover your medication can cost more than expected.
- Overlooking the out-of-pocket maximum. A high limit raises your worst-case cost.
- Assuming last year's benefits repeat. Plans change every year, so review your annual notice.
- Relying on old documents. Always use current-year plan materials.
For related pitfalls, see 4 Medicare HMO doctor mistakes that hurt your care.
Steps to Take Before You Decide
- Confirm the plan is offered in your county for the current plan year.
- Download the Summary of Benefits and Evidence of Coverage for that plan.
- Verify your doctors, hospital, and pharmacy are in network.
- Compare total costs, including the out-of-pocket maximum.
- Ask about extra benefits and any limits.
- Speak with a licensed Medicare adviser or the plan directly to confirm details.
You can also review the official plan documents and Medicare's own tools at Medicare.gov Plan Compare to see current-year options for your ZIP code.
Final Thoughts
The Cigna Preferred Savings Medicare HMO shows how a low-premium plan can pair $0 primary care visits with network rules and varying cost limits. The details change by county and year, so verify everything in official 2026 documents before you act. A plan works best when it fits your doctors, your medications, and your health goals.
Ready to build a strong primary care relationship, whatever plan you choose? Book your visit with InCare to start a personalized prevention plan, or contact our team with questions about care and insurance.
FAQs
Q: What is the Cigna Preferred Savings Medicare HMO?
A: It is a local Medicare Advantage HMO plan that combines Medicare-covered medical care with prescription drug coverage in the examples reviewed. Benefits, networks, and costs vary by county and plan year, so confirm details in official documents.
Q: Does the Cigna Preferred Savings Medicare HMO cover primary care visits?
A: In the 2025 examples reviewed, primary care visits cost $0 for in-person or telehealth appointments. You should confirm the current 2026 copay for your county and check that your doctor is in the plan's network.
Q: How much does the Cigna Preferred Savings Medicare HMO cost per month?
A: The plan examples reviewed listed a $0 monthly plan premium. Members generally still pay the Medicare Part B premium, and costs like specialist copays and the out-of-pocket maximum differ by area.
Q: Do I need referrals with this Medicare HMO?
A: HMO plans usually require you to use network providers, and some require referrals for specialists. Review the plan's Evidence of Coverage for the exact referral rules and any exceptions that apply to you.
Q: How do I know if my doctor accepts this plan?
A: Check the plan's current provider directory, then call your doctor's office to confirm they accept the exact plan name and ID. A phone call is a helpful second check because directories can lag behind recent changes.


