Key Takeaways
- Kaiser Permanente Senior Advantage is a Medicare Advantage (Part C) plan available only in certain Kaiser service areas, so confirm it is offered where you live before comparing options.
- Enrollment requires Medicare Part A and Part B, U.S. citizenship or lawful presence, and residence in the plan's service area; the Annual Enrollment Period runs October 15 to December 7.
- Costs vary by region and plan: a 2026 Northwest example shows premiums of $0, $37, and $119 with out-of-pocket maximums of $5,500, $4,500, and $3,500, so a lower premium often means a higher maximum.
- Members generally must use the plan's provider network, so check that your doctors and pharmacies are in network and review the formulary for your prescriptions before enrolling.
Choosing a Medicare plan is one of the biggest health decisions older adults make. Kaiser Permanente Senior Advantage is a name many people in Kaiser service areas hear often. It is a Medicare Advantage plan built around coordinated care, and it works very differently from Original Medicare. If you live in Tampa, Riverview, or anywhere else in Florida, you may be wondering how it fits into your primary care and wellness plans.
This guide explains nine key facts about Kaiser Permanente Senior Advantage in plain language. You will learn what the plan is, who can join, what it covers, and what it may cost. You will also learn what to compare before you enroll. Plan details change by region and by year, so always check the current Summary of Benefits for your area. By the end, you will know which questions to ask so your plan supports your health goals, not just your budget.
1. It Is a Medicare Advantage Plan, Not Original Medicare
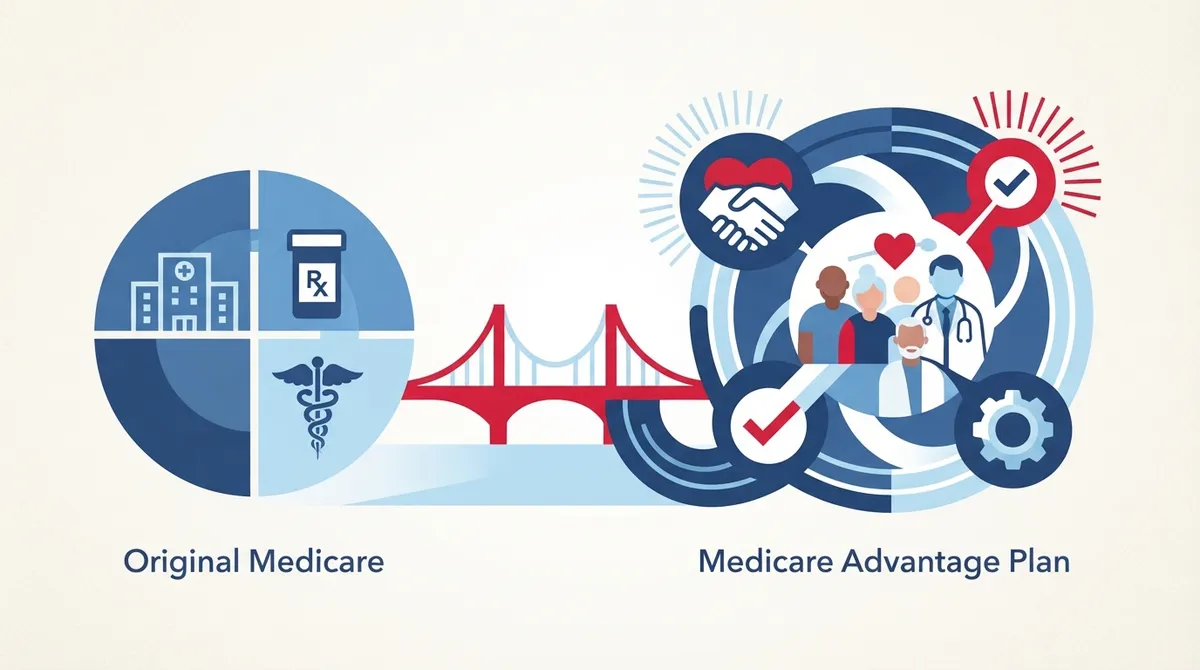
Kaiser Permanente Senior Advantage is a Medicare Advantage (Part C) plan. These plans are offered by private organizations that contract with Medicare. They generally combine Medicare Part A (hospital) and Part B (medical) coverage into one plan. Many also include Part D prescription drug coverage.
The exact benefits depend on your region and the plan you pick. Kaiser Permanente only offers Senior Advantage in certain service areas. That means the plan is not available everywhere in the country. Before you get attached to a plan, confirm it is offered where you live.
Here are the basic parts of Medicare to keep in mind:
- Part A: Hospital stays and some skilled nursing care.
- Part B: Doctor visits, outpatient care, and preventive services.
- Part C: Medicare Advantage, which bundles A and B and often more.
- Part D: Prescription drug coverage.
2. You Must Meet Eligibility Rules to Enroll
You cannot join just by wanting to. Kaiser Permanente Senior Advantage has clear eligibility rules. In general, you need Medicare Part A and Part B. You must also meet U.S. citizenship or lawful presence requirements. Finally, you must live in the service area of the specific plan.
Timing matters too. Medicare has set enrollment periods each year. The Annual Enrollment Period runs from October 15 to December 7 for coverage that starts the next year. Other special enrollment periods may apply if you move or lose other coverage. Check Medicare.gov or the plan's current materials for exact dates in 2026.
3. The Care Model Centers on Coordination
The biggest selling point of this plan is coordinated care. Each member has a personal physician who helps manage routine care. That doctor can coordinate referrals, hospital care, and other services. The goal is to keep your care connected instead of scattered.
Coordination matters because older adults often see several providers. When records and plans do not line up, mistakes can happen. A strong primary care relationship helps prevent that. It is the same idea behind coordinated care versus fragmented care. When one doctor knows your full story, you get safer and smarter decisions.
4. Preventive Services Are a Core Benefit
Medicare generally covers many preventive services with no cost-sharing when plan rules are met. Plan materials list examples such as annual wellness visits, screenings, vaccinations, and diabetes-related services. The exact list and requirements are in your Evidence of Coverage, so read it closely.
Prevention is where primary care shines. Catching problems early is often easier and less costly than treating them late. Common preventive steps include:
- Scheduling an annual wellness visit every year.
- Keeping up with recommended cancer screenings.
- Staying current on vaccines.
- Checking blood pressure, cholesterol, and blood sugar.
- Reviewing all medications with your doctor.
If you want to know what to expect at these visits, see what happens during an annual wellness visit. You can also review cancer screening options to plan ahead.
5. Costs Vary Widely by Region and Plan
There is no single national price for Kaiser Permanente Senior Advantage. Premiums, copays, and out-of-pocket limits change by region and by plan option. A regional example helps show the range. A 2026 Northwest benefit chart lists three Senior Advantage HMO-POS options with different premiums and limits.
|
Plan Option (2026 Northwest Example) |
Monthly Premium |
Annual Medical Out-of-Pocket Maximum |
|---|---|---|
|
Value |
$0 |
$5,500 |
|
Standard |
$37 |
$4,500 |
|
Enhanced |
$119 |
$3,500 |
These numbers are only a regional example, not Florida or nationwide rates. Notice the pattern, though. A lower premium often comes with a higher out-of-pocket maximum. A higher premium often gives you more protection if you get seriously ill. Think about your health needs and budget before choosing.
6. Prescription Drug Coverage Follows Stage Rules
Many Senior Advantage plans include Part D drug coverage. Part D works in stages. The same 2026 Northwest chart states that the initial coverage stage ends when covered drug costs paid by the member and plan reach $2,100. After that, members pay the applicable catastrophic-stage amount.
Do not assume your medicines are covered the same way in every plan. Each plan has a formulary, which is its list of covered drugs. Check that your current prescriptions are on the list. Also check which pharmacies are in network. Good medication habits help too, and these prescription management tips can keep your regimen safe and organized.
7. Optional Extras Like Dental, Vision, and Hearing May Cost More
Some plans offer optional supplemental benefits, such as dental, vision, or hearing coverage. These often require an additional premium. Availability, allowances, and costs differ by region and plan. Do not assume these extras come standard.
Ask these questions before you enroll:
- Is dental coverage included, or is it an add-on?
- What is the yearly allowance for eyewear or hearing aids?
- Do I need to use specific providers for these benefits?
- How much extra will the optional package cost each month?
Reading the fine print now can save you from surprise bills later.
8. Network Rules and Plan Quality Ratings Matter
Members generally receive covered care through the plan's provider network, subject to plan rules and exceptions. This is a key difference from Original Medicare, which lets you see any doctor that accepts Medicare. If your favorite doctor is outside the network, you may pay more or lose coverage for that visit.
Quality ratings can help you compare plans. Kaiser Permanente reported that its 2025 Medicare Advantage plans earned CMS Star Ratings of 4 or 4.5 stars, depending on region. For context, CMS reported that about 40% of Medicare Advantage prescription drug contracts offered in 2025 earned 4 stars or higher. Star Ratings are specific to each plan and year, so check the rating for the exact plan you are considering.
Learn more about the system behind these ratings on the official CMS Star Ratings fact sheet.
9. Local Primary Care Still Plays a Big Role in Your Wellness
Even with a strong plan, your health depends on the relationship you have with your doctor. Many Florida seniors want a primary care team that knows them well, offers time to talk, and uses modern tools. That is why it helps to understand your options before you commit to any plan.
InCare is a personalized clinic in Tampa and Riverview that combines technology with medical expertise. The team focuses on prevention and whole-body wellness. Services include primary care, urgent care, cancer screenings, DNA gene testing, and medical weight loss. If you want to see how other patients feel about the care, read InCare reviews on Google. You can also follow the practice on Instagram for health tips and updates.
If you are weighing Medicare options, it also helps to know what Medicare covers for seniors in primary care. And if you live in the Tampa Bay area, review these traits of a strong Medicare provider before you choose a doctor.
How to Compare Plans Before You Enroll
Use a simple process so you do not feel overwhelmed. Follow these steps:
- Confirm the plan is offered in your service area.
- Request the current Summary of Benefits and Evidence of Coverage.
- Check that your doctors and pharmacy are in network.
- Look up your prescriptions on the plan formulary.
- Compare premiums, copays, and the out-of-pocket maximum.
- Review the Star Rating for the exact plan.
Take your time with each step. A short checklist now can protect your health and your wallet for the whole year.
Conclusion
Kaiser Permanente Senior Advantage is a coordinated-care Medicare Advantage plan with preventive benefits, optional extras, and region-specific costs. It can be a strong fit for some people, but the details change by location and plan year. Always rely on the current Summary of Benefits for your area before you decide.
No matter which plan you choose, a trusted primary care relationship is the foundation of good health. If you live in Tampa or Riverview and want personalized, prevention-focused care, book an appointment with InCare today. You can also contact our team with questions about care that supports your Medicare journey.
FAQs
Q: What is Kaiser Permanente Senior Advantage, and how does it work?
A: Kaiser Permanente Senior Advantage is a Medicare Advantage (Part C) plan offered in specific Kaiser Permanente service areas. It generally combines Medicare Part A and Part B coverage and often includes Part D drug coverage. Members receive care through a coordinated network led by a personal physician.
Q: Who is eligible to enroll in Kaiser Permanente Senior Advantage?
A: You generally need Medicare Part A and Part B, must meet U.S. citizenship or lawful presence requirements, and must live in the plan's service area. Enrollment is limited to specific periods, such as the Annual Enrollment Period from October 15 to December 7. Check the current plan materials for your exact options.
Q: How much does Kaiser Permanente Senior Advantage cost?
A: Costs vary by region and plan option. A 2026 Northwest example lists monthly premiums of $0, $37, and $119, with annual medical out-of-pocket maximums of $5,500, $4,500, and $3,500. Review the Summary of Benefits for your location to see your actual costs.
Q: Can I see any doctor with Kaiser Permanente Senior Advantage?
A: Members generally receive covered care through the plan's provider network, subject to plan rules and exceptions. This differs from Original Medicare, which allows visits to any provider that accepts Medicare. Confirm that your preferred doctors are in network before you enroll.
Q: Does Kaiser Permanente Senior Advantage include dental, vision, and hearing coverage?
A: Some plans offer optional dental, vision, or hearing benefits for an additional premium. Availability, allowances, and costs vary by region and plan. Do not assume these benefits are included in every Senior Advantage plan.