Key Takeaways
- Verify your doctors are in-network before enrolling in Anthem Medicare Advantage HMO; calling offices to confirm acceptance of your specific plan can prevent full bills or forced provider switches.
- Confirm referral and prior authorization rules for your exact plan before scheduling specialist visits, as some 2026 Anthem plans require referrals while others do not, preventing denied claims.
- Review total annual costs beyond premiums, including copays, drug formulary tiers, and the $9,250 maximum out-of-pocket limit, to understand true expenses and plan accordingly.
- Choose a strong primary care provider who manages your health history, coordinates specialist care, and emphasizes preventive screenings to catch problems early and reduce hospitalization.
- Understand the difference between standard HMO and HMO-POS plans before enrolling; HMO-POS covers some out-of-network services at higher costs, offering more flexibility for travelers.
- Evaluate plan extras like dental, vision, hearing, OTC allowances, and transportation benefits by requesting exact dollar amounts in writing, as availability and value vary significantly by county.
Choosing a health plan is a big decision. For many seniors in Florida, an Anthem Medicare Advantage HMO looks like a simple way to get coverage and a few extra perks. But small mistakes can lead to surprise bills, delayed care, and frustration at the doctor's office. The good news is that most of these errors are easy to avoid once you know what to look for.
An Anthem Medicare Advantage HMO is a private Medicare Part C plan. It delivers your Medicare Part A and Part B benefits through Anthem. Many plans also include Part D drug coverage and extra benefits. The rules, costs, and networks change by plan and by county, so details matter.
This guide covers five common mistakes people make with an Anthem Medicare Advantage HMO in 2026. It also explains how primary care fits into the picture. Whether you live in Tampa, Riverview, or nearby, these tips can help you protect your health and your wallet.
What Is an Anthem Medicare Advantage HMO?
A Medicare Advantage HMO bundles your hospital and medical coverage into one private plan. HMO stands for Health Maintenance Organization. In plain terms, you use doctors and hospitals that belong to the plan's network. In return, you often pay lower copays and get extra benefits.
Here are the core features to understand before you enroll:
- Part A and Part B benefits: The plan must cover what Original Medicare covers.
- Network-based care: Routine care generally must come from in-network providers.
- Primary care provider (PCP): Most HMOs ask you to choose one doctor to lead your care.
- Possible extras: Some plans add dental, vision, hearing, over-the-counter allowances, fitness benefits, or transportation.
- Drug coverage: Many plans include Part D, but the formulary varies.
Anthem's 2026 materials show that most plans have a $0 in-network medical deductible. They also list primary care copays that range from $0 to $20 in example plan comparisons. Your exact costs depend on your plan and location, so always check the Summary of Benefits.
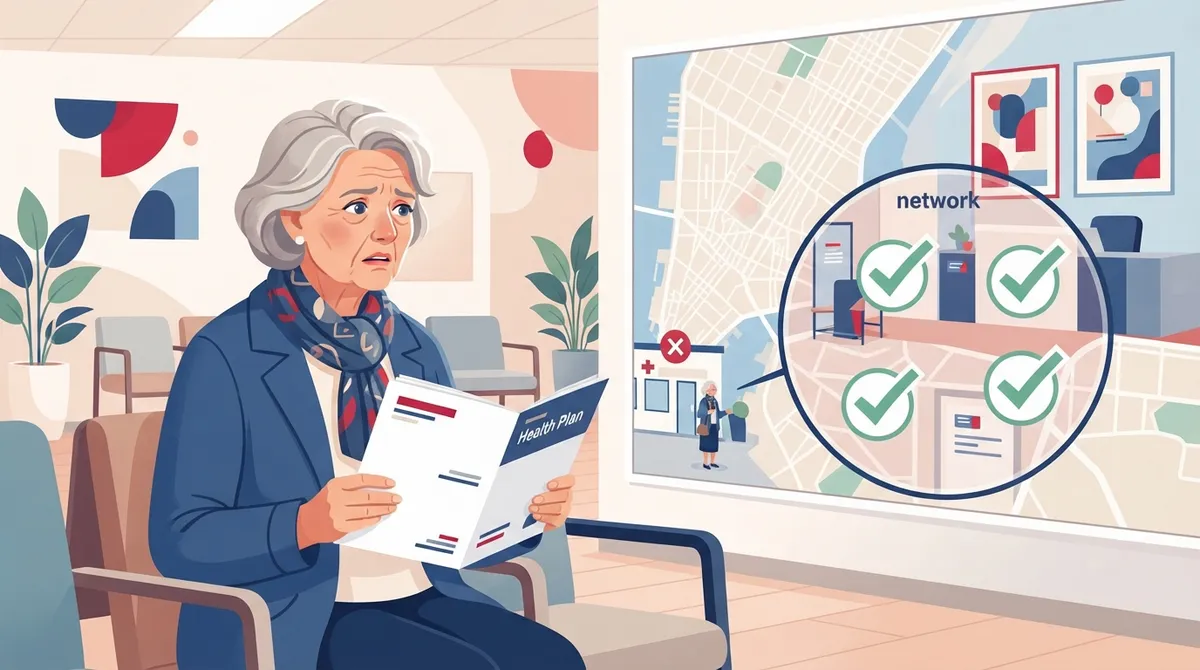
Mistake 1: Ignoring the Provider Network
The biggest error is assuming your current doctor is covered. Many people enroll first and check later. That order can backfire.
With an HMO, routine care outside the network is generally not covered. Standard HMOs only make exceptions for emergency care, out-of-area urgent care, and temporary out-of-area dialysis. If your trusted doctor is out of network, you may face the full bill or need to switch.
How to Avoid It
Verify your doctors before you enroll. Follow these steps:
- Write down the names of every doctor, specialist, and facility you use.
- Search for each one in Anthem's provider directory for your exact plan.
- Call the office and ask if they accept your specific plan name, not just "Anthem."
- Confirm the plan's service area includes your county.
- Keep a copy of the directory results for your records.
Networks can change during the year, so recheck them each fall. If you want help finding a trusted in-network provider, learn more in our guide on how to find the best Medicare HMO doctor in Riverview.
Mistake 2: Skipping the Primary Care Provider Choice
Most Medicare Advantage HMOs ask you to select a primary care provider. Some people ignore this step or pick a name at random. That is a missed opportunity.
Your PCP is your main point of contact. This doctor handles routine visits, manages long-term conditions, orders screenings, and helps coordinate specialist care. A good PCP relationship can catch problems early and keep you out of the hospital.
What a Strong PCP Relationship Looks Like
- A doctor who knows your full health history
- Same-day or short-wait appointment options
- Clear communication about medications and test results
- Support for preventive care, not just sick visits
- A team that helps you understand referrals and approvals
Preventive care matters even more as you age. Annual wellness visits, cancer screenings, and blood pressure checks can find issues before they grow. You can read more about this in our article on how to use a Medicare HMO for better primary care.
At InCare primary care, our providers focus on prevention and whole-body health. We pair medical expertise with modern technology to give you a clear picture of your health. You can meet our team on the providers page.
Mistake 3: Assuming Every Plan Follows the Same Referral Rules
Referral rules are one of the most confusing parts of an HMO. Medicare.gov says referrals are required in most HMOs. However, Anthem's 2026 materials show that some plans do not require them. The rule depends on your exact plan.
If you assume you do not need a referral and you do, you may get a denied claim. If you assume you do need one and you do not, you may waste time and delay care.
Referral and Authorization Quick Check
|
Question to Ask |
Why It Matters |
Where to Find the Answer |
|---|---|---|
|
Do I need a referral to see a specialist? |
Prevents denied claims |
Evidence of Coverage |
|
Which services need prior authorization? |
Avoids surprise bills |
Summary of Benefits |
|
Is my specialist in network? |
Out-of-network care is often not covered |
Anthem provider directory |
|
Who submits the referral? |
Speeds up scheduling |
Your PCP's office |
Before booking any specialist visit, call your plan or your PCP's office. A two-minute call can save you hundreds of dollars. For a deeper look at this topic, see our guide on whether you need a referral with a Medicare HMO in 2026.
Mistake 4: Confusing HMO and HMO-POS Plans
Many shoppers see "HMO" and "HMO-POS" and think they are the same. They are not. The difference can affect how much freedom you have.
A standard HMO generally does not cover out-of-network routine care unless the plan authorizes it. An HMO-POS (Point of Service) plan may cover certain out-of-network services. These services often cost more than in-network care, but the option exists.
|
Feature |
Standard HMO |
HMO-POS |
|---|---|---|
|
In-network care |
Required for routine services |
Preferred for lowest cost |
|
Out-of-network care |
Generally not covered, with exceptions |
Some services may be covered |
|
Out-of-network cost |
Not applicable in most cases |
Usually higher cost sharing |
|
PCP required |
Usually yes |
Varies by plan |
|
Best for |
People happy to stay in network |
People wanting some flexibility |
Neither type is better for everyone. If you travel often or split time between states, an HMO-POS may offer more flexibility. If you plan to stay close to home and use a local team, a standard HMO can work well. For more on this topic, read about in-network vs. out-of-network Medicare HMO doctors.
Mistake 5: Overlooking Costs, Limits, and Extra Benefits
The last mistake is focusing only on the monthly premium. A low premium does not tell the whole story. You also need to look at copays, drug costs, and yearly spending limits.
For 2026, the federal maximum out-of-pocket limit for Medicare Advantage in-network services is $9,250. Individual plans may set lower limits. Knowing this number helps you plan for a worst-case year.
Costs to Review Before You Enroll
- Monthly premium: What you pay each month for the plan.
- Primary care and specialist copays: What you pay at each visit.
- Medical deductible: Most 2026 Anthem plans list $0 in-network, but confirm yours.
- Drug formulary and tiers: Check that your medicines are covered and how much they cost.
- Maximum out-of-pocket limit: The most you could pay in a year for in-network care.
Do not skip the extras either. Dental, vision, hearing, OTC allowances, fitness benefits, and transportation can add real value. But availability and amounts depend on the plan, county, and eligibility. Ask for the exact dollar amounts in writing.
Key Dates and Steps for 2026
Timing matters when you choose a plan. Medicare's Annual Enrollment Period runs from October 15 through December 7 each year. This is the main window to join, switch, or drop a Medicare Advantage plan for the next year.
Use this simple checklist during enrollment season:
- Review your Annual Notice of Change when it arrives.
- List your doctors, medicines, and expected care needs.
- Compare plan networks, formularies, and costs side by side.
- Confirm referral and prior authorization rules.
- Ask your PCP's office which plans they accept.
- Enroll before December 7 to avoid missing the window.
If you are still unsure, ask for help from a licensed Medicare resource and talk to your doctor's office. Many practices can tell you which plans they work with most smoothly.
How a Primary Care Partner Makes Your Plan Work Harder
An HMO works best when you have a strong primary care partner. Your PCP can coordinate specialists, manage prescriptions, and track your screenings. That coordination is one of the biggest benefits of an HMO model.
InCare serves patients in Tampa and Riverview with comprehensive primary care, urgent care, and advanced wellness services. Our approach centers on prevention and personalized plans. Services include cancer screening, medical weight loss, and annual wellness visits. You can see how a yearly checkup works in our guide on what happens during an annual wellness visit.
We encourage every new patient to confirm their plan details before booking. Plan acceptance can change, so call the office or check with your insurer to verify your coverage. Our patients also share their experiences on social media, including Instagram and Facebook, and you can follow our health tips on TikTok.
Want to see what patients say about us? Read InCare reviews and visit us on Google. Our practice holds a 4.8 out of 5 rating with 359 reviews, with patients often praising our friendly staff and the care they receive from our physicians.
Conclusion: Protect Your Health and Your Wallet
An Anthem Medicare Advantage HMO can be a smart choice when you understand how it works. Check your network, pick a PCP you trust, verify referral rules, know the difference between HMO and HMO-POS, and look past the premium. Avoiding these five mistakes can save you money and stress in 2026.
Always confirm the details with your plan documents, since coverage varies by plan and county. Then pair your plan with a primary care team that puts prevention first.
Ready to take the next step? Book your appointment with InCare today, or contact our team with questions about care in Tampa and Riverview.
FAQs
Q: What does an Anthem Medicare Advantage HMO cover?
A: An Anthem Medicare Advantage HMO covers everything Original Medicare Part A and Part B covers. Many plans also include Part D drug coverage and extras such as dental, vision, hearing, and fitness benefits. Exact coverage varies by plan and county, so review your Summary of Benefits.
Q: Do I need to choose a primary care doctor with an Anthem Medicare HMO?
A: Most Medicare Advantage HMOs require you to select a primary care provider. This doctor coordinates your routine care and may help arrange specialist visits. Check your plan documents to confirm the rule for your specific plan.
Q: Do Anthem Medicare Advantage HMO plans require referrals to specialists?
A: It depends on the plan. Medicare.gov states that referrals are required in most HMOs, but Anthem's 2026 materials show that some plans do not require them. Verify your exact plan's rule before scheduling specialist care.
Q: Can I see a doctor outside the Anthem HMO network?
A: Standard HMOs generally do not cover routine out-of-network care. Exceptions typically include emergency care, out-of-area urgent care, and temporary out-of-area dialysis. HMO-POS plans may cover some out-of-network services, often at higher cost.
Q: What is the difference between Anthem HMO and HMO-POS Medicare plans?
A: A standard HMO usually requires you to stay in network for routine care. An HMO-POS plan may cover certain out-of-network services, though you will often pay more. Review the Evidence of Coverage to see which services qualify.