
Key Takeaways
- Verify your doctor is in-network before each visit, as out-of-network care can result in unexpected bills—this is the most costly mistake Molina Medicare Advantage members make.
- Don't assume all Molina plans are identical; benefits, copays, and extra perks vary by state and county, so always read your specific Summary of Benefits and compare plans yearly.
- Book your annual wellness visit early each year at no cost to catch health problems early and establish your yearly health plan, as many members skip this preventive benefit.
- Check referral and prior authorization rules with your primary care doctor before seeing specialists, as skipping this step can result in denied claims and unexpected costs.
Choosing a Medicare Advantage plan is a big decision. Choosing the wrong one, or using it the wrong way, can cost you time, money, and good care. Molina Medicare Advantage plans offer many benefits, but they also come with rules that catch many members off guard.
Molina Medicare Advantage plans are private plans that deliver Medicare Part A and Part B benefits. Many also include prescription drug coverage and extra wellness perks. Yet benefits, costs, and networks differ by county and by plan. A small oversight, like seeing a doctor outside the network, can lead to an unexpected bill.
This guide walks through 14 common mistakes that members make with Molina Medicare Advantage. You will learn how to avoid each one and get more from your primary care. Whether you are a busy professional helping a parent, a family planner, or a health-conscious adult, these tips apply. Read on to protect your health and your wallet in 2026.
What Is Molina Medicare Advantage?
Molina Medicare Advantage is a group of private health plans that replace Original Medicare for those who enroll. They cover the same hospital and medical services. Many also add benefits that Original Medicare does not include.
A 2026 review found that Molina offered Medicare Advantage plans in 20 states. Availability can change by county, so always check your local options. The same review estimated that about 70% of Molina plans had a $0 monthly plan premium. Members generally still pay the Medicare Part B premium.
Common Molina Plan Types
- HMO plans: These usually require you to use in-network providers and often need referrals for specialists.
- Dual Eligible Special Needs Plans (D-SNPs): These serve people who have both Medicare and Medicaid.
- Plans with Part D: About 98% of Molina plans included prescription drug coverage in 2026, according to the review.
Knowing your plan type is the first step. It shapes every choice you make about doctors, referrals, and costs.
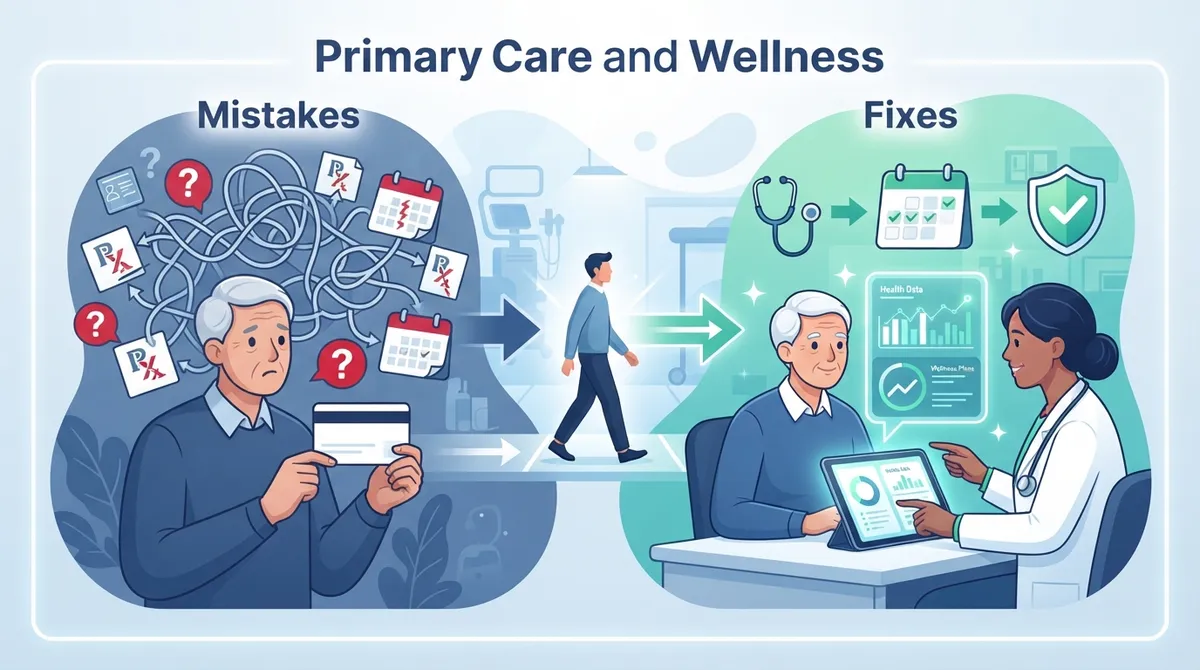
Quick Look: Mistakes and Their Fixes
|
Mistake |
Why It Hurts |
Simple Fix |
|---|---|---|
|
Skipping the network check |
Out-of-network bills |
Verify your doctor before each visit |
|
Assuming every plan is identical |
Wrong benefit expectations |
Read your own Summary of Benefits |
|
Ignoring referral rules |
Denied specialist claims |
Ask your primary care doctor first |
|
Missing the wellness visit |
Lost preventive care |
Book it every year |
|
Forgetting extra benefits |
Wasted perks |
Review dental, vision, and OTC options |
Mistakes About Choosing and Enrolling
1. Assuming All Molina Plans Are the Same
Plans differ by state and county. One member may have a $100 monthly over-the-counter allowance, while another has none. A 2026 Mississippi D-SNP example lists that $100 allowance, but it is not a standard benefit everywhere. Always read the Summary of Benefits for your exact plan.
2. Looking Only at the Premium
A $0 premium sounds great, but it is only part of the story. The review estimated an average maximum out-of-pocket limit of $7,546 for Molina plans. Compare copays, deductibles, and yearly limits too.
3. Ignoring Star Ratings
CMS star ratings reflect plan quality. The same review reported an enrollment-weighted average of 3.22 out of 5 for Molina plans in 2026. Ratings are plan-specific and change each year, so check the rating for your own plan.
4. Not Confirming Your Eligibility for a D-SNP
D-SNP eligibility generally requires both Medicare and Medicaid. Benefits depend on your plan and your Medicaid status. Confirm your status before you count on added benefits.
Mistakes About Networks and Referrals
5. Skipping the Network Check
This is the most costly error. Molina plans use provider networks. Verify that your primary care clinician, specialists, pharmacies, and preferred hospital are in network. Do this before each new type of care, not only at enrollment.
6. Forgetting Referral and Prior Authorization Rules
Many plans require referrals or approval for non-emergency services. Skipping this step can lead to denied claims. A strong relationship with a primary care doctor makes this process smoother. Learn more in this guide on how to use a Medicare HMO for better primary care.
7. Assuming Your Old Doctor Still Accepts Your Plan
Doctors change which plans they accept. Call the office and ask directly. Our guide on finding a doctor that accepts Medicare offers a simple process to follow.
8. Overlooking Care Coordination
Seeing many doctors without a lead provider can lead to repeated tests and gaps. Compare the two models in fragmented care vs. coordinated care.
Mistakes About Primary Care and Prevention
9. Believing a $0 Copay Means Everything Is Free
In 2026 plan examples, primary care visits often list a $0 copay. This is not universal, though. A free visit does not mean every service is free. Separately billed tests, procedures, or non-covered services may carry costs. Ask the office what may be billed on top of the visit.
10. Skipping the Annual Wellness Visit
A 2026 Molina member handbook states that the annual wellness visit has no copayment, coinsurance, or deductible. Confirm this in your own plan documents. This visit helps catch problems early and builds your health plan. See what happens during an annual wellness visit and avoid the common wellness visit mistakes.
11. Putting Off Preventive Screenings
Medicare-covered preventive care can include screenings and vaccines. Early detection saves lives and lowers long-term costs. Talk with your doctor about cancer screening and other tests that fit your age and risk.
|
Preventive Service |
Why It Matters |
|---|---|
|
Annual wellness visit |
Sets a yearly health plan |
|
Cancer screenings |
Finds disease early |
|
Vaccines |
Prevents serious illness |
|
Chronic condition checks |
Keeps blood pressure and sugar in range |
Mistakes About Benefits and Costs
12. Leaving Extra Benefits Unused
Some Molina plans offer extras. These may include dental and vision care, transportation to medical appointments, over-the-counter allowances, hearing benefits, telehealth, and health education. These perks differ by plan and location, and may have limits. Use them, since they are part of what you pay for.
- Check if dental and vision are included.
- Ask about rides to appointments.
- Use your OTC allowance if your plan has one.
- Try telehealth for simple follow-ups.
13. Mishandling Prescriptions
With most Molina plans including drug coverage, check your formulary and preferred pharmacies. Review your medicines each year. These prescription management tips can help you stay on track.
14. Not Reviewing Your Plan Each Year
Plans change every year. Benefits, networks, and costs can shift. Read your Annual Notice of Change and compare it with your needs. A plan that worked in 2025 may not be the best fit in 2026.
How to Check Your Molina Benefits Step by Step
- Find your Summary of Benefits and Evidence of Coverage for your exact plan.
- Confirm your primary care doctor is in network.
- Check referral and prior authorization rules for specialists.
- List the extra benefits you can use, such as dental, vision, or rides.
- Book your annual wellness visit early in the year.
- Review your drug list and preferred pharmacies.
Following these steps takes less than an hour. It can prevent surprise bills all year.
Why Primary Care Matters Most With Medicare Advantage
Your primary care doctor is the center of your plan. This provider manages referrals, tracks chronic conditions, and keeps your care organized. Strong primary care lowers the risk of costly emergency visits and hospital stays. See how primary doctors help manage chronic illnesses.
InCare is a personalized healthcare clinic in Tampa and Riverview, Florida. Our team combines modern technology with medical expertise to deliver primary care built around prevention. Many patients also look for a trusted option in their area, as shown in our guide to the best Medicare provider for primary care. Practices also help patients with eligibility and benefits checks, so you know what to expect before you walk in. Always confirm network status with your plan, since participation can change.
You can see what patients say about our care when you visit us on Google — InCare. Follow us on Facebook, Instagram, and TikTok for health tips and updates.
Make Your Plan Work for You
Molina Medicare Advantage can be a strong choice when you understand how it works. Most problems come from small oversights, like skipping the network check, missing the wellness visit, or ignoring referral rules. Fix these 14 mistakes and you protect both your health and your budget.
Remember that plan details vary. Always confirm costs and coverage in your own plan documents. Then pair your plan with a primary care team that knows you well. Ready to take the next step? Book Now to schedule a visit, or contact our team with questions about your care.
FAQs
Q: What does Molina Medicare Advantage cover?
A: Molina Medicare Advantage plans provide Medicare Part A and Part B benefits, and many include Part D prescription drug coverage. Some plans also add extras such as dental, vision, transportation, hearing, telehealth, and over-the-counter allowances. Benefits vary by plan and county, so review your Summary of Benefits.
Q: Are Molina Medicare Advantage primary care visits free?
A: Many 2026 plan examples list a $0 copay for primary care visits, but this is not true for every plan. A $0 copay does not mean all services during the visit are free, since tests or procedures may be billed separately. Confirm details in your Evidence of Coverage.
Q: Does Molina Medicare Advantage cover the annual wellness visit?
A: A 2026 Molina member handbook states that the annual wellness visit has no copayment, coinsurance, or deductible. Coverage can vary, so confirm it in your own plan documents. The visit is a useful way to catch health concerns early.
Q: How do I check if my doctor is in the Molina network?
A: Use the provider directory in your plan documents or call Molina member services. You can also call your doctor's office and ask whether they accept your exact plan. Check again before major care, since networks can change.
Q: Does Molina offer plans for people with both Medicare and Medicaid?
A: Yes. Molina offers Dual Eligible Special Needs Plans (D-SNPs) for people who have both Medicare and Medicaid. Benefits depend on the specific plan and your Medicaid status, so verify your eligibility before enrolling.


