
Key Takeaways
- Always verify your exact Blue Advantage HMO plan name, coverage type, and plan year on your member ID card before making care decisions, as Blue Advantage plans vary significantly by state and may be commercial or Medicare Advantage versions with different rules.
- Confirm your primary care provider participates in your specific HMO network by searching the current provider directory and calling both the office and plan, since accepting Blue Cross coverage generally does not guarantee participation in your specific plan.
- Understand that referrals and prior authorizations are separate requirements that vary by plan—check your Evidence of Coverage to determine which applies to your services, as some plans require neither while others require one or both.
- Review your plan's out-of-network coverage limits and preventive care benefits in your Summary of Benefits annually, since HMO plans typically restrict non-emergency out-of-network care and plan benefits change year to year.
Choosing a health plan is one of the most important decisions you will make for your long-term wellbeing. If you have come across the name Blue Advantage HMO, you may be wondering what it covers, how it works, and how it affects your primary care. The answer is not always simple. Blue Cross and Blue Shield companies operate independently, so benefits, networks, and rules vary by state, insurer, and plan year.
For busy professionals, young families, and wellness-minded adults, the stakes are practical. You want a primary care doctor you trust, easy access to preventive screenings, and no surprise bills. This guide walks through 11 key facts about Blue Advantage HMO so you can make confident, informed choices in 2026. You will learn how to verify your network, understand referrals, and get more value from your coverage. At InCare, we believe informed patients get better care, and we are glad to help you sort through the details.
1. Blue Advantage HMO Is Not One Single National Plan
The first thing to understand is that "Blue Advantage HMO" is not a uniform product across the country. Each Blue Cross and Blue Shield company sets its own plan designs, service areas, and provider networks. A plan with this name in one state may look very different from a plan with a similar name in another state.
Plan names can also refer to different coverage types. Some are commercial or employer-based plans. Others are Medicare Advantage plans. Always confirm the exact plan name, coverage type, and plan year before you make any care decisions.
2. Commercial and Medicare Advantage Versions Are Different
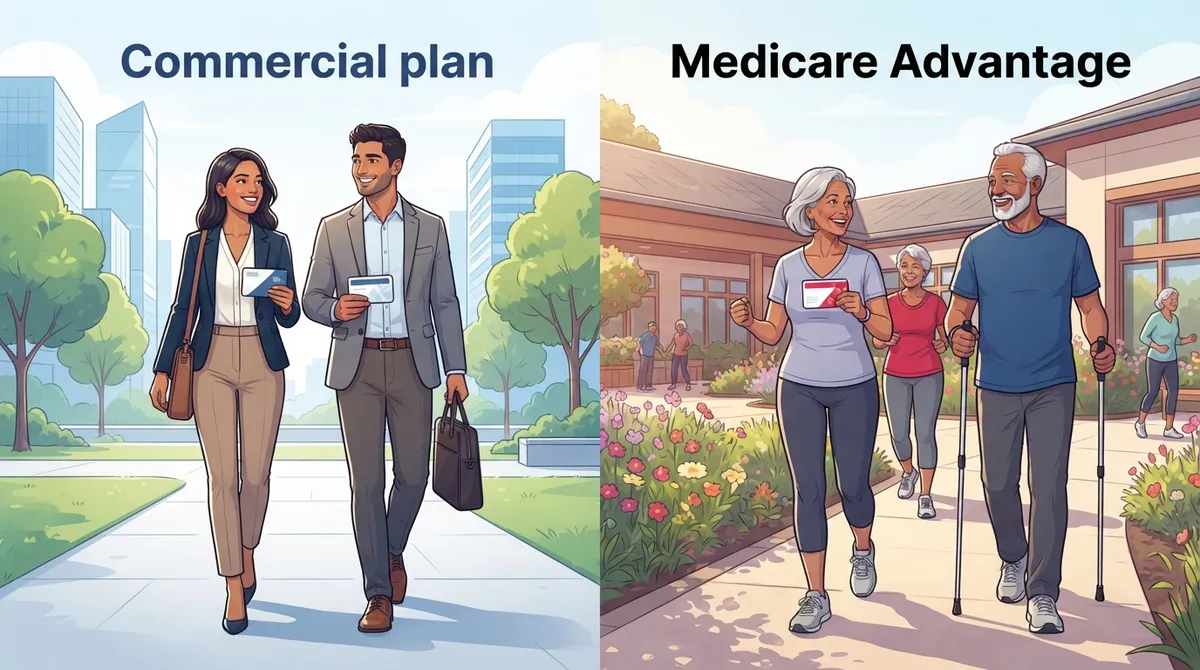
Some of the public documents tied to Blue Advantage are Medicare Advantage HMO-POS plans, including 2026 Evidence of Coverage materials from Louisiana. These are distinct from commercial network plans, such as the Blue Advantage HMO network listed by Blue Cross and Blue Shield of Texas.
Do not assume the rules for one apply to the other. Eligibility, costs, referral rules, and prior authorization can all differ. Your plan documents are the final word on your benefits.
|
Plan Type |
Who It Typically Serves |
What to Check |
|---|---|---|
|
Commercial HMO network |
Employer or individual coverage holders |
Network directory, service area, PCP participation |
|
Medicare Advantage HMO-POS |
Medicare-eligible adults |
Evidence of Coverage, referral rules, point-of-service options |
3. The Service Area May Be Broad, but Network Status Still Matters
In Texas, Blue Cross and Blue Shield of Texas provider directories state that the Blue Advantage HMO service area includes all 254 Texas counties. That sounds reassuring. However, a wide service area does not guarantee that your preferred doctor participates.
Network participation can vary by location and can change over time. Always use the current directory to confirm a specific clinician, office, or facility before you schedule care.
4. Your Primary Care Provider Sits at the Center of Care
HMO plans generally emphasize care through a defined network of providers. Your primary care provider (PCP) is usually your main point of contact. A strong PCP relationship helps you manage chronic conditions, stay current on screenings, and coordinate care in one place.
If you are still searching for the right fit, you can learn more in our guide on how to choose the right general practitioner for your care. Comprehensive primary care can also reduce the risk of fragmented care.
5. Verify Your PCP Before You Book
Follow these steps to confirm that a doctor works with your plan:
- Find your exact plan name and plan year on your member ID card.
- Open the current provider directory for that specific network.
- Search for the clinician by name and by office location.
- Confirm the provider is accepting new patients.
- Call the office and the plan to verify network status in writing if possible.
Remember that a provider accepting Blue Cross coverage in general does not prove participation in a specific HMO network. This single step can save you from unexpected costs. Our team also shares tips on finding doctors accepting new patients near you.
6. Out-of-Network Coverage Is Often Limited
Most HMO plans restrict coverage outside the network. Exceptions usually include emergencies and certain plan-specific situations. Non-emergency care from an out-of-network provider may not be covered at all.
Before you see a new specialist or visit a new facility, check your plan documents. Ask whether the service is covered and whether a point-of-service option applies. A quick call can prevent a large bill later.
7. Referral Rules Are Plan-Specific
Many people assume an HMO always requires a PCP referral for every specialist visit. That is not always true. The 2026 Louisiana Blue Advantage HMO-POS Evidence of Coverage states that referrals are not required for network providers. However, prior authorization may still apply to certain services.
Other plans may have stricter rules. Read your Evidence of Coverage or certificate of coverage carefully. If you are unsure, your PCP's office can often explain how referrals work for your specific plan.
8. Prior Authorization Can Apply Even Without Referrals
Prior authorization means your plan must approve certain services before you receive them. This can include advanced imaging, procedures, or specialty treatments. A referral and a prior authorization are not the same thing.
- A referral is a recommendation from your PCP to see a specialist.
- A prior authorization is an approval from your insurer for a specific service.
- Some plans require one, both, or neither, depending on the service.
Ask your doctor's office to help you check authorization needs before major tests or treatments. This is especially helpful for busy families who cannot afford delays.
9. Preventive Care Deserves a Close Look
Preventive care is where many patients gain the most value. Wellness visits, screenings, and early detection can catch problems before they become serious. Coverage for these services varies by plan, so review your Summary of Benefits.
Look for details on annual exams, immunizations, and screenings. Learn what to expect during an annual wellness visit and how cancer screening can support early detection. For a broader view, see our article on making preventive care work for your health.
10. Costs Vary, So Read the Fine Print
Premiums, deductibles, copayments, and out-of-pocket maximums differ widely. No single number applies to every Blue Advantage HMO member. Costs depend on your state, exact plan name, coverage type, and plan year.
|
Document |
What It Tells You |
|---|---|
|
Summary of Benefits |
A quick overview of costs and covered services |
|
Evidence of Coverage |
Detailed rules, limits, and member rights |
|
Annual Notice of Change |
What is changing from one plan year to the next |
|
Provider Directory |
Which doctors and facilities are in your network |
Review these documents each year. Plans change, and a benefit that helped you last year may look different in 2026.
11. Advanced Wellness Services May Fall Outside Your Plan
Many people today want more than basic care. Services such as DNA gene testing, IV hydration and vitamin drips, and metabolic breath analysis support whole-body optimization. Coverage for these services depends on the plan and the medical need, and some may be self-pay.
Ask your clinic and your insurer how each service is billed before you begin. Clear expectations help you plan your budget and avoid surprises. If weight management is one of your goals, explore our weight loss programs to see how a personalized approach works.
How to Get the Most From Your HMO Plan
A good plan is only as helpful as the care you actually use. These habits can make a real difference:
- Schedule your annual wellness visit early in the plan year.
- Keep your PCP informed about every specialist you see.
- Save copies of referrals, authorizations, and explanation-of-benefits forms.
- Ask about same-day and virtual options when you need quick answers.
- Review your plan documents again each fall before open enrollment.
If you want a practice that blends modern technology with a personal touch, InCare offers primary care and urgent care in Tampa and Riverview. You can explore our locations or read what patients say on Google by visiting our InCare Google Business Profile. You can also connect with our community on Instagram, Facebook, and TikTok.
Conclusion
Blue Advantage HMO can be a solid path to coordinated, affordable care, but only if you understand how your specific plan works. Verify your exact plan name and year, confirm your PCP is in network, and review referral, authorization, and cost rules before you book. A few minutes of research can protect both your health and your budget.
Ready for a primary care partner who focuses on prevention and whole-body wellness? Book your appointment with InCare today, or contact our team with any questions about coverage and care.
FAQs
Q: What is Blue Advantage HMO health insurance?
A: Blue Advantage HMO is a Blue Cross-branded HMO product whose details vary by state, insurer, coverage type, and plan year. It is not one uniform national plan. Always check your official plan documents for exact benefits and rules.
Q: Is my primary care doctor in the Blue Advantage HMO network?
A: You can confirm this by searching the current provider directory for your exact plan and then calling the office and your insurer. Accepting Blue Cross coverage in general does not guarantee participation in a specific HMO network. Also confirm the provider is accepting new patients.
Q: Do I need a referral to see a specialist with Blue Advantage HMO?
A: It depends on your plan. The 2026 Louisiana Blue Advantage HMO-POS Evidence of Coverage says referrals are not required for network providers, though prior authorization may still apply to certain services. Review your own plan documents for the rules that apply to you.
Q: Does Blue Advantage HMO cover out-of-network care?
A: Out-of-network coverage is often limited under HMO plans, with exceptions such as emergencies and plan-specific circumstances. Some plans include a point-of-service option for certain services. Check your plan documents before you receive any non-emergency out-of-network care.
Q: How can I check my Blue Advantage HMO benefits and costs?
A: Review your Summary of Benefits, Evidence of Coverage, and current provider directory for your exact plan year. These documents explain covered services, cost sharing, referral rules, and prior authorization requirements. You can also call the number on your member ID card for clarification.


